How to Calculate Net Worth: The Complete Step-by-Step Guide
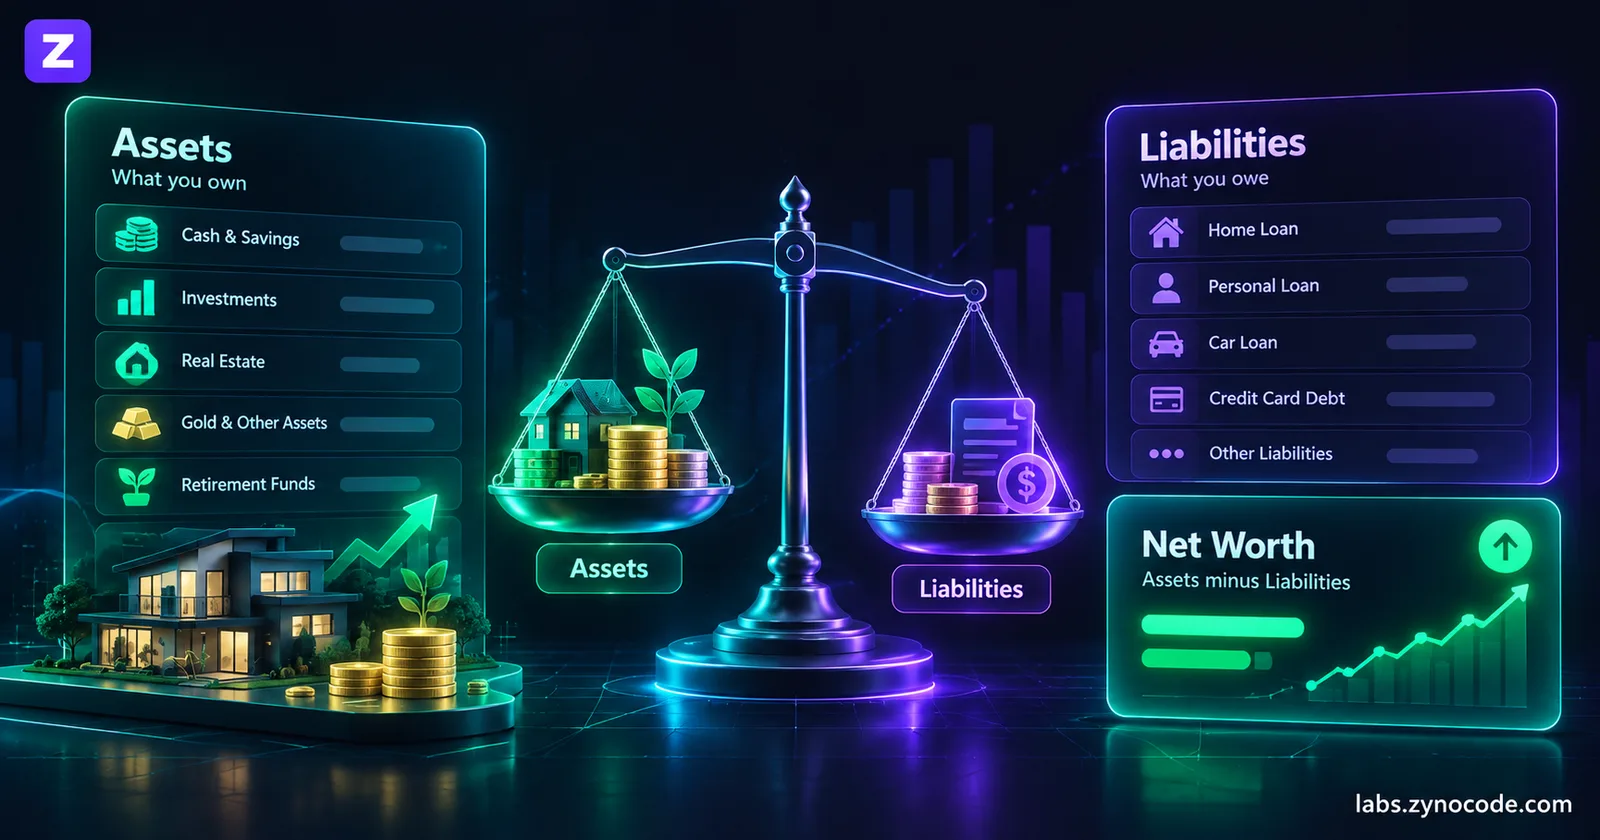
To calculate your net worth, add the current market value of everything you own (assets) and subtract the total amount of everything you owe (liabilities). The resulting number represents your true financial standing. A positive net worth indicates that assets exceed debts, while a negative net worth means debt outweighs owned assets.
Learning how to calculate net worth provides the clearest snapshot of your overall financial health. While annual income shows how much money flows into your bank accounts, net worth reveals how much wealth you actually retain after accounting for what you owe. Whether you are building an emergency fund, eliminating credit card debt, or planning for retirement, you can calculate and visualize your wealth in seconds using our free Net Worth Calculator.
What Is Net Worth? Assets vs. Liabilities Explained
Net worth is the total monetary value of an individual or household after deducting all liabilities from all owned assets.
To understand net worth, you must separate your finances into two distinct categories:
- Assets (What You Own): Anything you own that has positive economic value and can be converted into cash. This includes liquid cash, savings deposits, brokerage portfolios, retirement accounts, real estate, and vehicle equity.
- Liabilities (What You Owe): Any financial obligation, outstanding balance, or debt you are legally required to repay. This includes credit card balances, mortgages, auto loans, personal loans, and student debt.
The Fundamental Net Worth Formula:
[ Total Assets ]  minus  [ Total Liabilities ]  =  [ Personal Net Worth ]
(Everything Owned)       (Everything Owed)          (True Accumulated Wealth)
Income alone does not determine wealth. A professional earning $200,000 annually who spends $210,000 and carries heavy consumer debt may have a negative net worth. Conversely, a modest earner who consistently saves and avoids excessive leverage builds positive wealth over time.
What to Include in Your Calculation
Accurate tracking requires listing every material asset and debt. Avoid inflating asset values or omitting smaller balances.
1. Typical Assets to Include
- Liquid Cash & Cash Equivalents: Checking balances, high-yield savings accounts, money market funds, and physical emergency cash.
- Retirement Savings: Tax-advantaged retirement accounts, employer-sponsored plans (such as 401k, 403b, or traditional/Roth IRAs), and pension transfer values.
- Investment Portfolios: Taxable brokerage accounts, individual stocks, mutual funds, exchange-traded funds (ETFs), and bond holdings.
- Real Estate Equity: The current fair market value of your primary residence, vacation home, or rental properties (not what you originally paid).
- Vehicles & Personal Property: The conservative trade-in or resale value of cars, motorcycles, or boats. Highly depreciating items like clothing and consumer electronics are typically excluded.
2. Typical Liabilities to Include
- Mortgage Loans: The total outstanding principal balance on primary or secondary home mortgages.
- Consumer & Credit Card Debt: Unpaid credit card balances, retail store credit, and Buy Now Pay Later (BNPL) installments.
- Vehicle Loans: Remaining balances on auto financing, car leases, or motorcycle loans.
- Student Loans: Federal and private student loan principal amounts.
- Personal & Medical Loans: Outstanding medical debt, bank personal loans, or family promissory notes.
Step-by-Step Worked Example
To see how the arithmetic works in practice, examine this illustrative household financial profile. This example uses the exact default configuration provided in our Net Worth Calculator.
Step 1: List and Total All Assets
- Checking Account: $2,500
- Savings Account: $10,000
- Retirement (401k/IRA): $45,000
- Real Estate (Home Market Value): $350,000
- Total Assets: $2,500 + $10,000 + $45,000 + $350,000 = $407,500
Step 2: List and Total All Liabilities
- Credit Card Debt: $3,500
- Auto Loan: $15,000
- Student Loans: $28,000
- Mortgage Balance: $280,000
- Total Liabilities: $3,500 + $15,000 + $28,000 + $280,000 = $326,500
Step 3: Subtract Liabilities from Assets
- Net Worth Calculation: $407,500 - $326,500 = $81,000
In this illustrative scenario, the household possesses an accumulated net worth of $81,000. Although the family carries substantial mortgage and student debt ($326,500), their home equity and retirement savings outweigh their debt obligations, creating a stable, positive wealth position.
While our calculator displays figures with the dollar symbol ($), the mathematical equation applies universally across all global currencies, whether you calculate in Indian Rupees (₹), Euros (€), or British Pounds (£).
Official Net Worth Benchmarks by Age
Comparing your finances to national benchmarks helps contextualize your savings trajectory. When examining wealth statistics, it is vital to distinguish between the median (the exact middle household) and the mean (the average, which is heavily skewed upward by ultra-high-net-worth individuals).
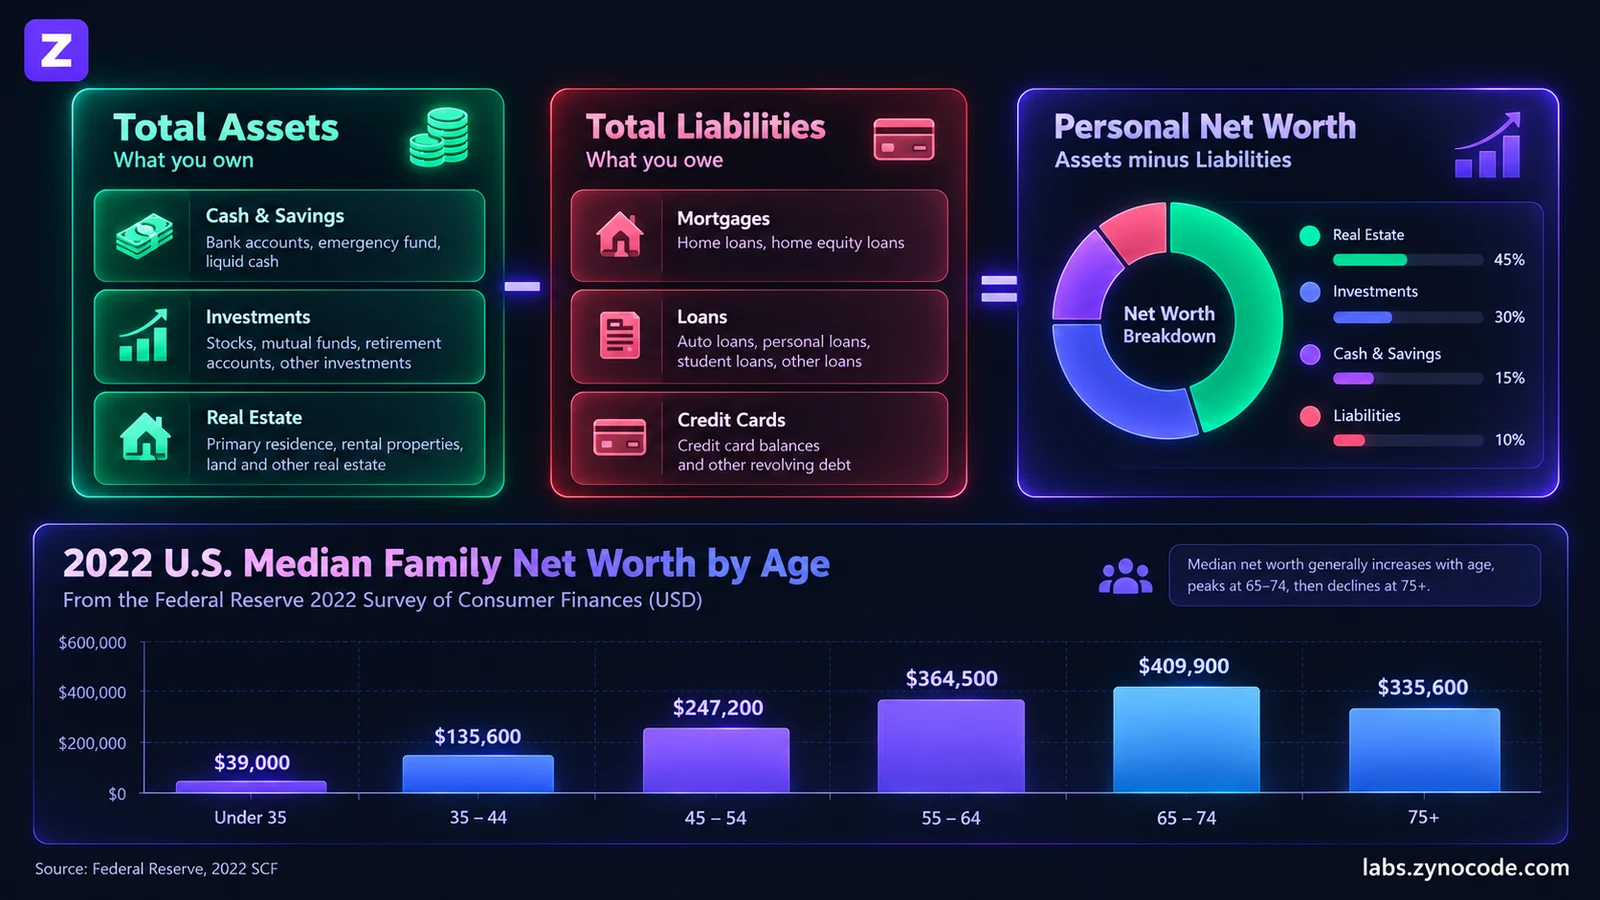
According to official data published by the Federal Reserve Board in the Federal Reserve Bulletin from the 2022 Survey of Consumer Finances report (PDF), "Between 2019 and 2022, real median net worth surged 37 percent" across U.S. families, climbing to an overall median of $192,900.
The 2022 Survey of Consumer Finances reports the following median and average net worth figures by age of the household head:
| Age of Household Head | Median Net Worth (2022 SCF) | Average (Mean) Net Worth (2022 SCF) | Primary Financial Focus |
|---|---|---|---|
| Under 35 | $39,000 | $183,500 | Paying off student loans, establishing an emergency fund, early retirement saving |
| 35–44 | $135,600 | $549,600 | Building home equity, advancing career earnings, expanding investment portfolios |
| 45–54 | $247,200 | $975,800 | Peak earning years, aggressive retirement catch-up, managing college expenses |
| 55–64 | $364,500 | $1,566,900 | Pre-retirement consolidation, debt elimination, estate and healthcare planning |
| 65–74 | $409,900 | $1,794,600 | Peak accumulated wealth, transition to retirement drawdowns, capital preservation |
| 75 and older | $335,600 | $1,624,100 | Retirement spending, legacy planning, managing medical and assisted living costs |
Because a small percentage of multi-millionaires elevates the mean average by hundreds of thousands of dollars, the median is usually the more realistic benchmark for everyday households.
Practical Strategies to Increase Your Net Worth
Building positive net worth does not require complex speculative trading. It relies on widening the gap between what you own and what you owe:
- Eliminate High-Interest Consumer Debt: Revolving credit cards charging 20% or more interest drain your monthly wealth building. Use a structured Debt Payoff Calculator to prioritize debts via the avalanche or snowball method.
- Save and Invest on a Schedule: Setting aside a fixed amount every month, rather than whenever money is left over, steadily grows the asset side of your balance sheet. What you invest in depends on your goals and risk tolerance. Indian investors can model recurring compounding growth using our SIP Calculator.
- Establish Concrete Savings Milestones: Quantify specific targets for home down payments, emergency funds, or capital purchases using our Savings Goal Calculator.
- Avoid Lifestyle Inflation: When your salary increases, resist the urge to immediately upgrade vehicles or housing. Saving a fixed share of every raise lets your net worth grow faster than your spending.
- Protect Assets with Adequate Insurance: A single medical emergency, property disaster, or liability claim can wipe out years of savings. Reviewing whether your insurance cover matches your situation is part of protecting your net worth.
How Our Free Net Worth Calculator Works
Our free browser-based Net Worth Calculator provides a distraction-free environment for financial tracking:
- Customizable Assets and Liabilities: Pre-populated with common accounts (checking, savings, retirement, home value, auto loans, and mortgages). You can easily add, rename, or delete custom items to match your exact portfolio.
- Dynamic Real-Time Calculation: Automatically tallies Total Assets and Total Liabilities, recalculating your Net Worth instantly as you type. If debts exceed assets, the net worth balance turns red to signal negative equity.
- Interactive Visual Breakdown: Generates a real-time responsive donut chart comparing Total Assets (emerald green) against Total Liabilities (red), helping you visualize your debt-to-asset ratio.
- 100% Client-Side Privacy: Financial balances should never be exposed. The calculator runs completely in your web browser. No bank logins are required, no cookies track your balances, and zero numbers are transmitted to our servers.
Summary
Calculating your net worth replaces financial anxiety with objective clarity. By systematically tracking assets against liabilities, you can monitor the long-term impact of your debt payoff and savings strategies.
Ready to check your financial standing? Open our free browser-based Net Worth Calculator, enter your current balances, and visualize your wealth in complete privacy. For more financial calculators, planning guides, and developer utilities, explore our full directory of free developer and financial tools.
Frequently asked questions
What is the basic formula to calculate net worth?+
The formula is Total Assets minus Total Liabilities. Total assets include everything you own that has cash value, while total liabilities include all debts and outstanding loans. The difference is your personal net worth.
Should I include my primary home when calculating net worth?+
Yes, if you own real estate, include its estimated market value under assets and your remaining mortgage balance under liabilities. Some financial planners also track non-home net worth to measure purely liquid retirement readiness.
Can your net worth be negative?+
Yes. A negative net worth happens when total debts exceed total assets, which is common for recent graduates with student loans or early career professionals. Paying down high-interest debt gradually shifts net worth into positive territory.
How often should you calculate your net worth?+
There is no fixed rule. Many people find a quarterly or twice-yearly check enough: frequent enough to spot trends, without reacting to short-term market swings.
Does our net worth calculator save my financial data?+
No. Our calculator operates entirely inside your web browser. None of your account balances, asset figures, or personal debt amounts are stored on servers or transmitted across networks.
Prashant Sharma · Founder & Technology Strategist
Prashant Sharma is the founder of Zynocode IT Solutions, specializing in web development, SEO tooling and generative AI workflows.